ServicesHard Money Loans
Hard Money Loans in Georgetown, TX
Hard money is short-term investor financing where the lender weighs the property and the project more heavily than your pay stubs. Before you sign, we lay out the rate, points, draw rules and exit, so the monthly cost of carrying the deal is clear from day one.
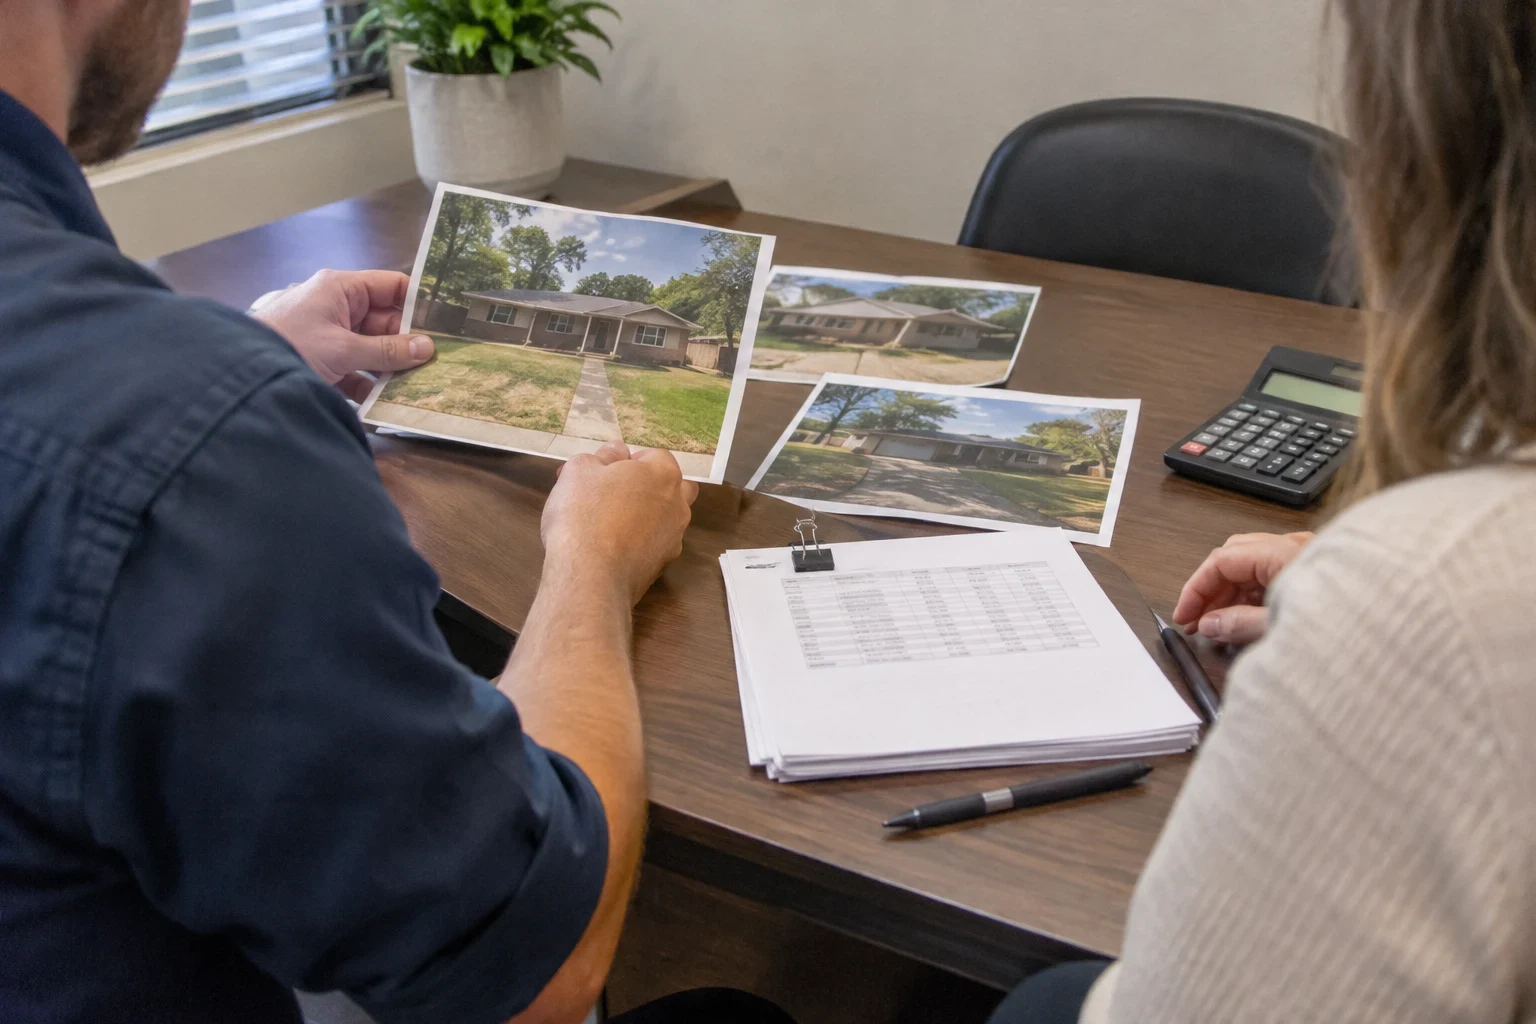
How hard money works and who it suits
A typical mortgage is underwritten around the person: paychecks, debts and credit. Hard money flips that order. The lender starts with the asset itself, the price you agreed to, the renovation budget and the value once the work is finished. Because of that focus, approvals can come quicker, and deals a bank would decline can still get funded.
You pay for that flexibility. Terms are usually measured in months, payments are often interest-only, and both the rate and the fees sit well above a conventional loan. It is worth it when timing or condition outweighs getting the cheapest rate: a tired property that would fail a standard appraisal, an offer with a short closing window, or a flip you expect to list within twelve months.
This is financing for investors. Planning to move in yourself? A Conventional Loan or FHA Loan is nearly always the cheaper and better fit, and we will point you there.
What we walk through together
Numbers checked up front
Before any application, we review the price you are paying, the renovation scope and the resale or rent you expect. When the profit looks too slim to absorb a surprise, we say so early, while backing out still costs you nothing for an appraisal.
LTV and LTC in plain terms
Lenders limit the loan against both the purchase price and the value after renovation. We turn those caps into a clear figure for the cash you will need at closing.
How renovation funds get paid out
Rehab money typically sits in a holdback and goes out in rounds after each phase passes an inspection. We explain that timing up front so your contractor is not stuck waiting between payments.
Fees written down
Points, interest, extension charges and any prepayment terms go on paper. You can add up what the loan costs for the months you plan to hold it.
A realistic way out
Each hard money loan ends in a sale or a refinance. We pressure-test that ending with you, including whether moving into a longer-term loan later is likely to work.
When hard money tends to make sense
It won't appraise in its current shape
A missing kitchen, a failing roof or foundation trouble can sink a standard appraisal. Hard money lenders are used to funding properties that need real work.
Your closing date is close
Auctions and fast-close offers rarely leave time for weeks of traditional underwriting.
You expect to sell inside a year
On a short hold, the setup costs of a 30-year loan may never pay off.
Your income is tough to document
Uneven or newly started income can trip up standard paperwork. If a longer-term loan is still the goal, compare a Bank Statement Loan as well.
You want to buy before you sell
Buying your next residence before the current one closes is usually a job for a Bridge Loan. We can explain how the two differ.
From first call to payoff
- 1
Talk through the deal by phone
Share where the property is, the contract price, the renovation you have in mind and whether you plan to sell or refinance. We tell you what a lender will want and point out any soft spots.
- 2
Application and paperwork
Your loan officer takes your application with you over the phone, one question at a time. You then gather the purchase contract, a written budget and scope, plus details on past projects and the funds you have available.
- 3
Valuation and terms review
The property gets an as-is value and, for rehab deals, a projected finished value. We read through the terms with you line by line, so the rate, points and draw rules are clear before you commit.
- 4
Closing, draws and exit
At closing you cover your portion of the price and costs. As the work moves along, money is released after each stage is verified, and the loan is paid off when you sell or refinance.
What shapes your rate and fees
Lenders price hard money on two things: how risky the deal looks and how long you will keep the loan. Lower risk and a shorter hold usually earn better terms. Instead of guessing at a range, we give you rate quotes for your specific deal by phone.
- Your cash in the deal
- A bigger down payment or more existing equity reduces the lender's exposure. That tends to help both the rate and the points.
- Scope of the renovation
- Fresh paint and flooring on a sound structure is priced differently than a full gut with structural work.
- Your track record
- Lenders feel more comfortable when you have completed and sold or rented a few projects already. A first flip can still get funded, but the pricing usually reflects that it is new ground for you.
- Time on the loan
- Interest builds every month the loan stays open. If the schedule slips, extension fees get added on top, so build a timeline you can actually hit.
Questions investors ask about hard money
Something not covered here? (512) 528-3761
Can I live in a property I buy with hard money?
No. These loans are meant for investment or business use, not a primary residence. If you plan to move in, we will go over conventional, FHA, VA or USDA options with you. Any of them will cost far less over the life of the loan.
How much does my credit score count?
Less than it would on a traditional mortgage, but a lender will still pull it. Your cash reserves and past projects get a look too. Most of the weight, though, sits on the property and the numbers behind the deal.
How quickly can a hard money loan close?
Typically faster than a standard mortgage, since the review centers on the property rather than months of income history. The real timeline depends on the appraisal, the title work and how fast your documents arrive. Once we see the deal, we will give you a straight answer.
What if the renovation takes longer than planned?
Many of these loans offer extensions, though they usually carry a fee and sometimes a higher rate. We review those terms with you before closing, so a delay on the job does not turn into a surprise on the bill.
Can I move into a long-term loan once the work is done?
Yes, and plenty of investors who plan to rent the property do exactly that. Whether a refinance works depends on the finished value, the rent it brings in and your own ability to qualify. We look at that before you start, not after.
Bring us your next investment deal
Share the property, the numbers and how you plan to exit. We will show you what a hard money loan would look like on it, for a purchase in Georgetown or nearby in Round Rock or Leander.